
Understanding the Issues in Illinois
Auto Insurance Rates in Illinois: Expected Future Costs Versus Past Financial Results
At State Farm, we understand that the price of insurance matters to our customers, especially as families continue to manage rising household expenses. We also recognize that an auto insurance rate increase may be frustrating or confusing, particularly after recent rate decreases and the announcement of a dividend for eligible State Farm Mutual auto customers.
We want customers to understand why these decisions can happen at the same time and what they mean for their insurance costs.
Insurance rates are reviewed regularly and reflect the expected future claims costs and expenses of insurers. Rate increases and decreases are based on a variety of factors and trends, such as repair and rebuilding costs, labor costs, weather patterns, legal system abuse, and more.
The 2025 dividend recently issued for eligible State Farm Mutual Automobile Insurance Company policyholders was based on past company results and is one way State Farm returns value to our customers.
A dividend and a rate adjustment serve different purposes. State Farm Mutual issued a dividend based on past financial results. An auto insurance rate adjustment, on the other hand, looks ahead at expected future claims costs and expenses in a particular state. This means State Farm can return value to customers based on past results while also adjusting rates to reflect anticipated future claims costs and expenses in Illinois.
Several factors can influence the cost of auto insurance in Illinois, including vehicle repairs, medical expenses, claims trends, severe weather and the rising costs associated with legal system abuse. These expenses don't always follow the same trends as general inflation, and conditions can vary significantly from state to state. That's why insurance rates are evaluated based on the specific expected future claims costs and expenses in Illinois, rather than national trends.
We know that even small rate adjustments can have a meaningful impact on household budgets. While an overall rate change may be announced for Illinois, not every customer's premium will change by the same amount. Individual premiums depend on several factors, including vehicles, drivers, location, driving history, selected coverages, deductibles, and available discounts.
Insurance rate adjustments are necessary to reflect expected future claims costs and expenses so an insurer can pay future claims and be there for its customers.
State Farm is also working with Illinois elected officials to reduce insurance costs by supporting “drivefulness” initiatives that can help prevent crashes while advocating for stronger protections against legal system abuse that drive unnecessary costs and higher premiums.
We're here to help you understand your options. If your premium changes, we encourage you to contact your State Farm agent to review your policy, explore available discounts and consider coverage or deductible options that may better fit your needs and budget.
At State Farm, our commitment remains the same: to provide customers with dependable coverage and personal service when they need it most.
Working with Illinois
State Farm continues to work with regulators and legislators in Illinois to help our customers.
- State Farm made a rate filing in early June 2025 indicating a Homeowners rate increase in Illinois. That filing was more than 32-pages long and is available publicly on the National Association of Insurance Commissioners (NAIC) SERFF site. It includes detailed actuarial analysis supporting the rate filing.
- On June 23, State Farm also submitted a 5-page response to questions the Department asked about the filing. No additional questions were received and the filing was closed out by the Department of Insurance on June 27.
- State Farm first learned of concerns with the rate filing through the Governor's press release in July. Since then, State Farm met with both the Director of the Illinois Department of Insurance and a Deputy Governor. There were no additional requests for information in that meeting.
- State Farm has provided the same type of information as other insurers provide in supporting rate filings in Illinois. Over the last three years, many insurers have raised Homeowners rates, citing deteriorating loss trends in Illinois; several of those increases in total exceed the State Farm increase.
- State Farm's retained counsel on these issues submitted a letter on July 31 to the Director of the Illinois of Department of Insurance clarifying our position and once again indicating our continued willingness to work with state officials.
- Unrelated to the June rate filing, the Illinois Department of Insurance in March 2024 demanded nationwide data of State Farm. This demand exceeds the legal authority of the Illinois Department of Insurance. State Farm has, therefore, not provided this data, but has asked the Illinois DOI to engage in a process that would allow an independent third-party/judge to resolve this dispute. State Farm made that request of the Department nearly one year ago.
An update to auto insurance rates
Auto insurance rates in Illinois will decrease an average of 5.7%, with some customers seeing reductions in premiums of up to 15%. Rate adjustments will apply to new and existing policies starting July 18, 2025. This decision is driven by trends projecting lower claims costs.
So, why are homeowner prices going up in Illinois?
Thank you for your trust in State Farm®. We understand no one likes to see their insurance rates increase, and we don’t take these decisions lightly. That’s why we want to provide you with some context around our approach in Illinois, where we are decreasing average auto insurance rates, and increasing average home insurance rates.
As a mutual company, State Farm is focused on serving its policyholders. Unlike companies with shareholders, our goal is not to maximize profits but to earn enough to maintain financial strength that allows us to keep the promises we make and to support future growth.
As we continue to adapt to changing conditions, we remain committed to providing you with the best possible value, service, and support. Thank you for allowing us to protect what matters most to you.
Home insurance rates are on the rise in Illinois due to rising home replacement costs and more frequent severe weather events that are driving up the cost and frequency of claims. These changes reflect broader trends in loss patterns and repair costs and are necessary to help ensure we can continue providing reliable coverage to our policyholders.
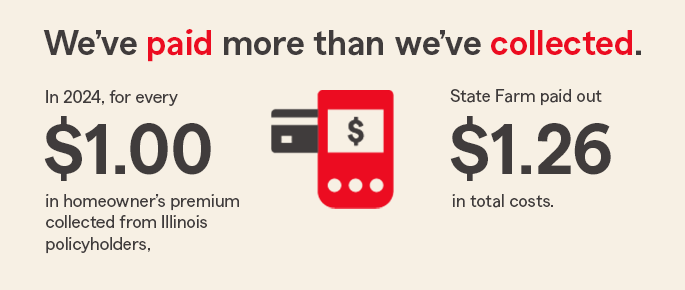
Home insurance claims costs are exceeding premiums collected. The cost of covering Illinois homeowners’ losses is exceeding the premiums we’re earning—an indication we need to adjust prices. Last year, those total costs amounted to $1.26 for every dollar in premium we collected. The year before, it was $1.30. Such losses are unsustainable.
Inflation matters. The costs of materials and labor have risen, affecting how much it costs to repair or rebuild homes. In the insurance business, the rates we charge are set in advance to cover potential future losses, including the costs to rebuild homes. As repair costs continue to rise, home insurance rates are as well.
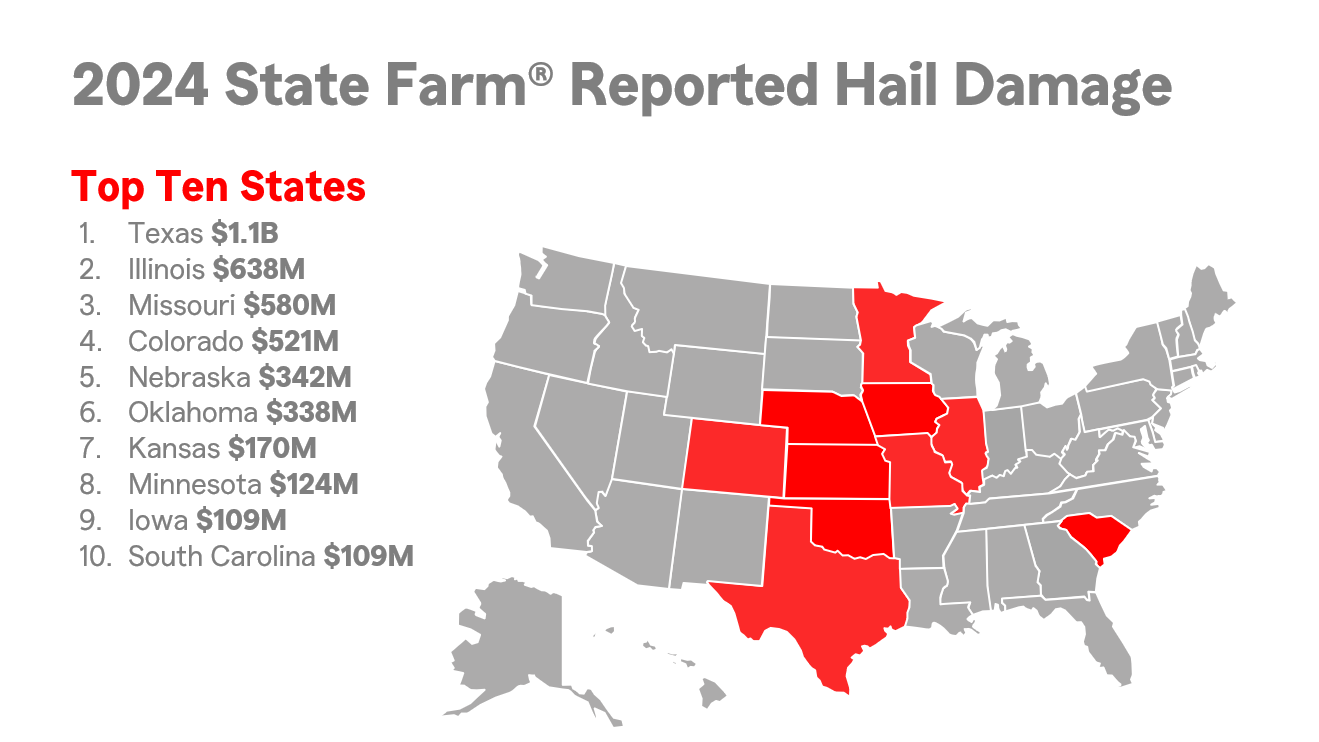
Severe weather—wind/hail and tornadoes—is increasing in Illinois. Trends in recent years indicate damaging storms are more frequent here. In fact, Illinois had more hail damage claims than any other state except Texas in 2024.
Illinois premiums are priced for the risk in this state—not for losses in other states, including wildfires, earthquakes, or hurricanes.
Contact your agent to discuss coverage options
State Farm is committed to being a responsible steward of the resources we manage, ensuring we can continue to provide the coverage you need in the face of increasing risks.
We encourage you to reach out to your State Farm agent to discuss your coverage options. Our team is here to help you navigate these changes and find the solutions that work best for you.
Wind and hail deductible explained…
One of the ways we are limiting rising premiums is through the introduction of a Wind/Hail Deductible. Illinois home insurance customers already choose deductibles related to loss perils. Illinois customers will now be required to have a minimum 1% Wind/Hail deductible as part of their home insurance policy. It will apply in instances where the cause of loss is deemed to be wind or hail. All other losses will be subject to the other deductible(s) stated within the policy.
Choosing a higher deductible is one way to reduce the premium you pay for insurance. Your State Farm agent can discuss options that are available.